Revised Timeline Regarding Implementation of Amended Section 6050W(e)

Member Submission • December 1, 2023

Part III - Administrative, Procedural, and Miscellaneous
SECTION 1. PURPOSE


This notice announces that calendar year 2023 will be regarded as a further

transition period for purposes of Internal Revenue Service (IRS) enforcement and

administration with respect to the implementation of the amendments made to the

minimum threshold for reporting by third party settlement organizations (TPSO) under

section 6050W(e) of the Internal Revenue Code (Code) 1 by the American Rescue Plan

Act of 2021 (ARP), Public Law 117-2, 135 Stat. 4 (March 11, 2021). The transition

period described in this notice is intended to facilitate an orderly transition for TPSO

compliance with section 6050W(e) and participating payee compliance with income tax

reporting.


SECTION 2. BACKGROUND


.01 Section 6050W, Returns relating to payments made in settlement of payment

card and third party network transactions


Section 6050W was added to the Code by section 3091 of the Housing Assistance

Tax Act of 2008, Div. C of Public Law 110-289, 122 Stat. 2654, 2908, and requires

payment settlement entities to file an information return for each calendar year with

respect to payments made in settlement of certain reportable payment transactions.

Under section 6050W(a), the annual information return must set forth (1) the name,

address, and taxpayer identification number (TIN) of the participating payee to whom

payments were made and (2) the gross amount of the reportable payment transactions

with respect to that payee in that calendar year. Section 1.6050W-1(a)(6) defines

“gross amount” to mean the total dollar amount of the aggregate reportable payment

transactions for each participating payee, without regard to any adjustments for credits,

cash equivalents, discount amounts, fees, refunded amounts, or any other amounts.


Payment settlement entities required to make annual information returns under

section 6050W do so by filing Form 1099-K, Payment Card and Third Party Network

Transactions with the IRS. They are also required to furnish Form 1099-K to the

participating payee. Forms 1099-K must be furnished to the participating payees on or

before January 31st of the year following the calendar year for which the return was

made. Forms 1099-K must be filed with the IRS on or before February 28th (March

31st if filed electronically) of the year following the calendar year for which the return

was made. See § 6050W(f); § 1.6050W-1(g).


Pursuant to section 6050W(c), section 6050W covers two types of reportable

payment transactions: (1) payment card transactions and (2) third party network

transactions. Section 6050W(c)(3) states that a third party network transaction is any

transaction for the provision of goods or services that is settled through a third party

payment network. Under section 6050W(b) and § 1.6050W-1(c)(2), a TPSO is the

payment settlement entity that must report third party network transactions – that is, the

transactions for goods or services that are settled through the TPSO’s third party

payment network – on Form 1099-K.


Section 6050W(b)(3) defines a TPSO as the central organization that has the

contractual obligation to make payment to the participating payees of third party network

transactions. Pursuant to section 6050W(d)(3), a third party payment network is any

agreement or arrangement that (i) involves the establishment of accounts with a central

organization by a substantial number of providers of goods or services who are

unrelated to the central organization and who have agreed to settle transactions for the

provision of goods and services with purchasers according to the terms of agreements;

(ii) provides standards and mechanisms for settling such transactions; and

(iii) guarantees payments to the providers of goods and services in settlement of

transactions with the purchasers.


Under section 6050W(d)(1)(A)(ii), a participating payee, in the case of a third party

network transaction, is any person who accepts payment from a TPSO in settlement of

such transaction.


As originally enacted in 2008, section 6050W(e) provided that a TPSO is not

required to report third party network transactions with respect to a participating payee

unless the gross amount that would otherwise be reported exceeds $20,000 and the

number of such transactions with that participating payee exceeds 200.


.02 Section 3406, Backup withholding


Section 3406(a) requires certain payers to perform backup withholding by deducting

and withholding income tax from a reportable payment when, among other

circumstances, the payee fails to furnish the payee’s TIN to the payer or the IRS has

notified the payer that the TIN furnished by the payee is incorrect. Pursuant to section

3406(b)(3)(F), a reportable payment includes payments made by a TPSO that are

required to be shown under section 6050W on a Form 1099-K. A payer is required to

report the amount of deducted and withheld Federal income tax amounts on Form 945,

Annual Return of Withheld Federal Income Tax, and on the information return filed with

the IRS and furnished to the payee. In the case of the Form 1099-K, withheld income

tax is reported in box 4. The payee may then claim credit for the amount of income tax

withheld on the payee’s Federal income tax return.


.03 Section 6721, Failure to file correct information returns, and section 6722,

Failure to furnish correct payee statements


Section 6721 imposes a penalty for any failure to file an information return on or

before the required filing date, and for any failure to include all of the information

required to be shown on the return or the inclusion of incorrect information.


Section 6722 imposes a penalty for failure to furnish a payee statement on or before

the required furnishing date to the person to whom such statement is required to be

furnished, and for any failure to include all of the information required to be shown on a

payee statement or the inclusion of incorrect information.


.04 American Rescue Plan Act of 2021


Section 9674 of the ARP amended section 6050W(e) to provide that, for Forms

1099-K for calendar years beginning after December 31, 2021, a TPSO is required to

report payments in settlement of third party network transactions with respect to any

participating payee that exceed a minimum threshold of $600 in aggregate payments,

regardless of the aggregate number of such transactions.


Notice 2023-10, 2023-3 I.R.B. 403 (January 17, 2023), delayed implementation of

the reporting threshold for TPSOs in section 9674(a) of the ARP for Forms 1099-K for

calendar years beginning before January 1, 2023. Notice 2023-10 also provided that

the IRS would not assert penalties under section 6721 or section 6722 for TPSOs failing

to file or failing to furnish Forms 1099-K unless the gross amount of aggregate

payments required to be reported exceeded $20,000 and the number of transactions

exceeded 200.


SECTION 3. TRANSITION PERIOD FOR ENFORCEMENT AND ADMINISTRATION

WITH RESPECT TO CALENDAR YEAR 2023


Calendar year 2023 will be regarded as a further transition period for purposes of

IRS enforcement and administration of the information reporting requirements under

section 6050W(e), as amended by the ARP. For calendar year 2023, a TPSO is not

required to report payments in settlement of third party network transactions with

respect to a participating payee unless (1) the gross amount of aggregate payments to

be reported exceeds $20,000 and (2) the number of such transactions with that

participating payee exceeds 200. The IRS will not assert penalties under section 6721

or section 6722 for a TPSO for failing to file or failing to furnish Forms 1099-K with

respect to a payee unless the gross amount of aggregate payments to be reported

exceeds $20,000 and the number of such transactions with that participating payee

exceed 200.


The IRS will not regard calendar year 2023 as a transition period with respect to the

requirements of section 6050W that were not modified by section 9674(a) of the ARP,

such as provisions relating to payment card transactions. In addition, TPSOs that have

performed backup withholding under section 3406(a) for a payee during calendar year

2023 must file a Form 945 and a Form 1099-K with the IRS and furnish a copy to the

payee if total reportable payments to the payee exceeded $600 for the calendar year.


SECTION 4. DRAFTING INFORMATION


The principal author of this notice is the Office of Associate Chief Counsel

(Procedure and Administration).


1  Unless otherwise specified, all “section” or “§” references are to sections of the Code or the Income Tax

Regulations (26 CFR part 1).

By Jaydee Wood • October 21, 2026
Now Accepting Applications & Nominations for 2026 Chamber Awards
October 19, 2026
Woman-owned business selected from more than 12,000 applicants nationwide for its resilience, innovation and commitment to workforce development SUMMERVILLE, S.C. — A Summerville small business is earning national recognition for its resilience, innovation and commitment to developing the next generation of skilled workers. Sew Fabulous LLC, a woman-owned alterations, bridal and embroidery business, has been named one of America's Top 100 Small Businesses through the U.S. Chamber of Commerce's prestigious 2026 CO—100 program. Selected from more than 12,000 applicants nationwide, Sew Fabulous is being recognized as a 2026 Champions of Adaptability honoree , a distinction celebrating businesses that have demonstrated exceptional resilience, determination and innovative problem-solving in overcoming challenges. Founded in 2015 by British-born entrepreneur and military veteran Angela Humphries, Sew Fabulous has grown from a small alterations operation in her home into a thriving business offering everyday tailoring, bridal and formalwear alterations, corporate embroidery, uniform services and custom branding solutions. A defining part of Sew Fabulous's success has been its investment in workforce development and preserving the skilled trade of sewing. Recognizing a growing shortage of experienced sewing professionals, Humphries developed the curricula for two U.S. Department of Labor Registered Apprenticeship programs, creating structured career pathways for individuals interested in professional sewing and alterations. To date, the company has supported 11 apprentices through its training initiatives, including five who successfully graduated in 2026. The company also established Sew Fabulous Academy, an initiative designed to expand access to sewing education, strengthen technical skills and introduce new generations to career opportunities in the industry. Rather than relying solely on an increasingly limited pool of experienced workers, Humphries has made workforce development a central component of the company's long-term growth strategy. Humphries will travel to Washington, D.C., in October to participate in the U.S. Chamber of Commerce's CO—100 celebrations alongside fellow entrepreneurs and business leaders from across the country. About Sew Fabulous LLC Founded in 2015, Sew Fabulous LLC is an award-winning, woman-owned business headquartered in Summerville, South Carolina. The company specializes in everyday alterations, bridal and formalwear alterations, corporate embroidery, uniforms and branded apparel. Through its two U.S. Department of Labor Registered Apprenticeship programs and Sew Fabulous Academy, Sew Fabulous is committed to preserving skilled trades, developing talented professionals and creating meaningful career opportunities. The company has earned more than 1,300 five-star Google reviews and numerous business recognitions. About Angela Humphries Beyond her business accomplishments, Humphries has demonstrated an enduring commitment to serving her community. Humphries was also honored with the Community Service Award by Summerville Chief of Police Doug Wright. She was one of the first two civilians to receive the award, recognizing her dedication to serving and strengthening the local community.  Her community involvement includes supporting individuals experiencing hardship, contributing to charitable initiatives, and working alongside organizations dedicated to strengthening the local community. For Humphries, business success is measured not only through growth and profitability but also through the opportunities created for others and the positive impact a company can have on its community.
October 15, 2026
Summerville S.C.- Dorchester Habitat for Humanity is grateful to St. Paul’s Anglican Church for their generous $1,000 donation in support of the organization’s Building the American Dream initiative. This contribution will help Dorchester Habitat continue its mission of building safe, affordable homes for families in Dorchester County. Through the Building the American Dream initiative, the organization is expanding homeownership opportunities and helping local families create a stronger foundation for their futures. “We are incredibly grateful to St. Paul’s for its generosity and commitment to our community,” said Erin Roach, Director of Development and Marketing. “Support from local churches and community partners move our mission forward and bring us one step closer to a future where more families have a safe, affordable place to call home.” Dorchester Habitat partners with qualifying families to achieve homeownership through home construction, financial education, and a 30-year, zero-interest mortgage. Homebuyers also contribute at least 425 hours of sweat-equity, working alongside volunteers and staff to help build homes. The organization’s Building the American Dream initiative reflects its continued commitment to transforming Dorchester County one home at a time. Through the generosity of churches, businesses, individuals, and volunteers, Dorchester Habitat is creating lasting opportunities for families to establish stability, build equity, and pursue brighter futures.  Learn more about Dorchester Habitat at www.dorchesterhabitat.org
By Jaydee Wood • October 13, 2026
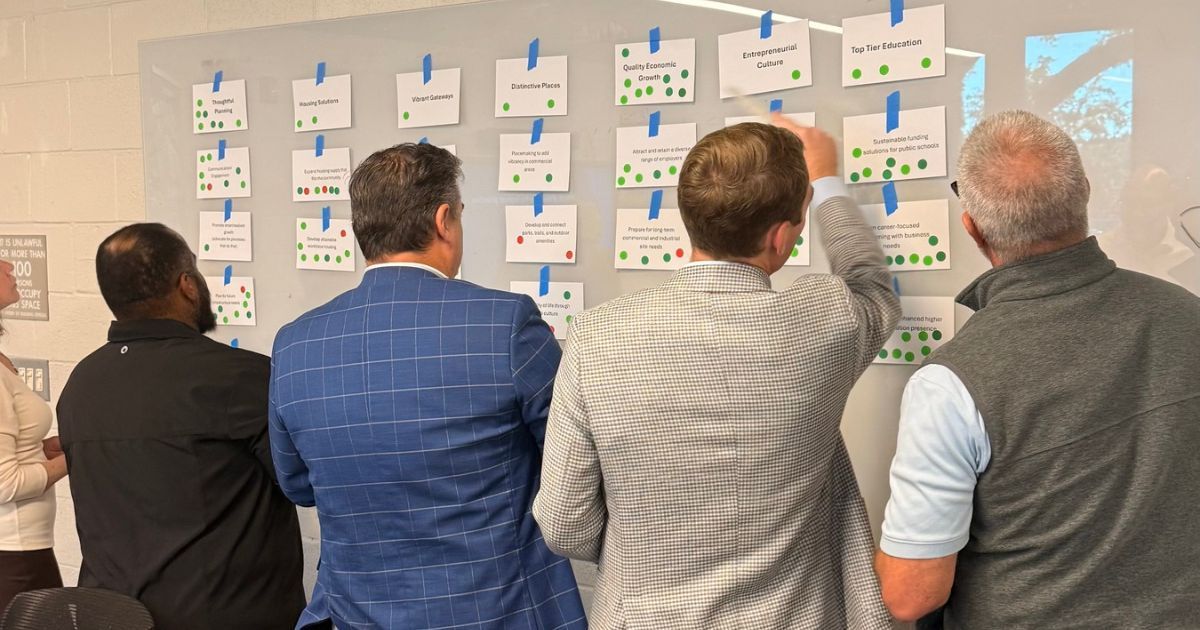
SUMMERVILLE, S.C. — 10/13/2026 — As it enters the final year of its current three-year strategic plan, the Greater Summerville/Dorchester Chamber of Commerce is already looking ahead. Chamber leadership, board members, staff, and stakeholders recently convened for a comprehensive planning session to map out the organization's vision and priorities for the next three years. Facilitated by Claire Louder of Louder Nonprofit Strategies, the session was designed to align the Chamber’s future trajectory with the region's explosive growth and evolving community needs. To ensure alignment with the region, the day kicked off with vital insights. Attendees heard directly from representatives of the Town of Summerville, Dorchester County, and Berkeley County regarding their current municipal and county-wide plans, ensuring the Chamber’s roadmap complements ongoing local government initiatives. Discussions were also guided by the goals of Envision 2047, keeping key components at the forefront. The planning conversation heavily emphasized: Thoughtful planning and smart growth Housing accessibility and variety Vibrant gateways and distinctive places Quality economic growth Fostering a robust entrepreneurial culture Top-tier education “We were very intentional about incorporating ENVISION 2047 as a guiding tool for our planning as it strategically parallels with what the business community and our members value and feel is important to achieve long-term success," said Rita Berry, President and CEO of the Greater Summerville/Dorchester Chamber of Commerce. In addition to regional collaboration and big-picture visioning, the session focused inward on member value. Leadership closely analyzed feedback and data from the Chamber’s most recent membership survey, brainstorming innovative ideas and actionable plans to enhance membership benefits and elevate programs for local businesses. More details regarding the official launch and specific pillars of the Summerville Chamber’s next strategic plan will be announced in the coming months. About the Greater Summerville Dorchester County Chamber of Commerce The Greater Summerville/Dorchester County Chamber of Commerce is a five-star accredited chamber dedicated to advancing economic prosperity through business advocacy, leadership development, workforce initiatives, and meaningful member engagement. Serving businesses of every size and industry, the Chamber works to create a stronger community throughout Summerville and Dorchester County. About Envision 2047 ENVISION 2047 is a long-term community vision and strategic action plan developed to guide the future of Summerville and Dorchester County over the next 20 years and beyond. Led by the Greater Summerville/Dorchester County Chamber Foundation, in partnership with Dorchester County and the Town of Summerville, along with a steering committee of business and community leaders, the initiative reflects a unified commitment to thoughtful, sustainable growth.
October 13, 2026
RIDGEVILLE, S.C. - Knight’s Companies is pleased to announce the rebranding and name change of Murray Mines to Knight’s Materials, effective immediately. The name change reflects the company’s continued growth in the construction materials industry and brings the operation under the Knight’s Companies brand. Knight’s Materials will continue to provide quality sand and other construction material products to customers throughout the region, with the same commitment to service, quality, and reliability that customers have come to expect. “We’re excited to officially bring Knight’s Materials into the Knight’s Companies family,” said Pete Knight, President and CEO of Knight’s Companies. “This is a natural next step as we continue to grow our materials business and expand the products and services we can provide to our customers and partners.” Customers can expect a seamless transition, with existing operations, relationships, and service continuing under the new Knight’s Materials name. Knight’s Materials is part of Knight’s Companies, a South Carolina-based construction materials and services company serving customers throughout the Southeast. Visit knightscompanies.com for more info on other products and services.
By HCA Healthcare • October 7, 2026
Investment in cardiothoracic and vascular surgery strengthens comprehensive cardiovascular care and expands access for Lowcountry patients
By Ragland Homes • October 7, 2026
SUMMERVILLE, S.C. - Local custom residential builder Ragland Homes has been named a recipient of the 2026 "Builder of Integrity" Award by Quality Builders Warranty (QBW). This marks the second time the Summerville-based home builder has earned the prestigious national honor, reinforcing its reputation for technical excellence, financial stability, and steadfast commitment to client trust across the Lowcountry. The Builder of Integrity Award is an exclusive recognition presented to a selective group of residential builders nationwide. Award recipients undergo a rigorous screening and ongoing performance review process evaluating technical skill, ethical business practice, craftsmanship, and customer service. "Building a custom home is one of the most significant investments a family will make and earning the trust of our clients is at the center of everything we do," said Bryan Ragland. "Receiving the Builder of Integrity Award for a second time validates our team's daily commitment to transparent communication, superior craftsmanship, and doing things right". This national recognition follows a period of strong local support for Ragland Homes, which was also voted Best Home Builder by readers of the Summerville Journal Scene for three years in a row. To learn more about Ragland Homes visit Raglandhomes.com or contact the team at (843) 284.3133. For details regarding the Quality Builders Warranty Builder of Integrity program, visit www.qbwc.com/BOI About Ragland Homes Founded in 2018, Ragland Homes is a premier custom home builder, led by Certified Master Builder Bryan Ragland based in Summerville, South Carolina. Serving clients throughout the Lowcountry, Ragland Homes specializes in custom home construction, build-on-your-lot projects, and personalized design solutions built on a foundation of integrity, quality, and transparency. About Quality Builders Warranty Corporation Quality Builders Warranty Corporation (QBW) is the nation’s premier 10-year new home warranty program. Operating since 1985, QBW screens builders nationwide to ensure members demonstrate superior craftsmanship, technical excellence, and financial integrity, providing structural warranties backed by Liberty Mutual.
October 1, 2026
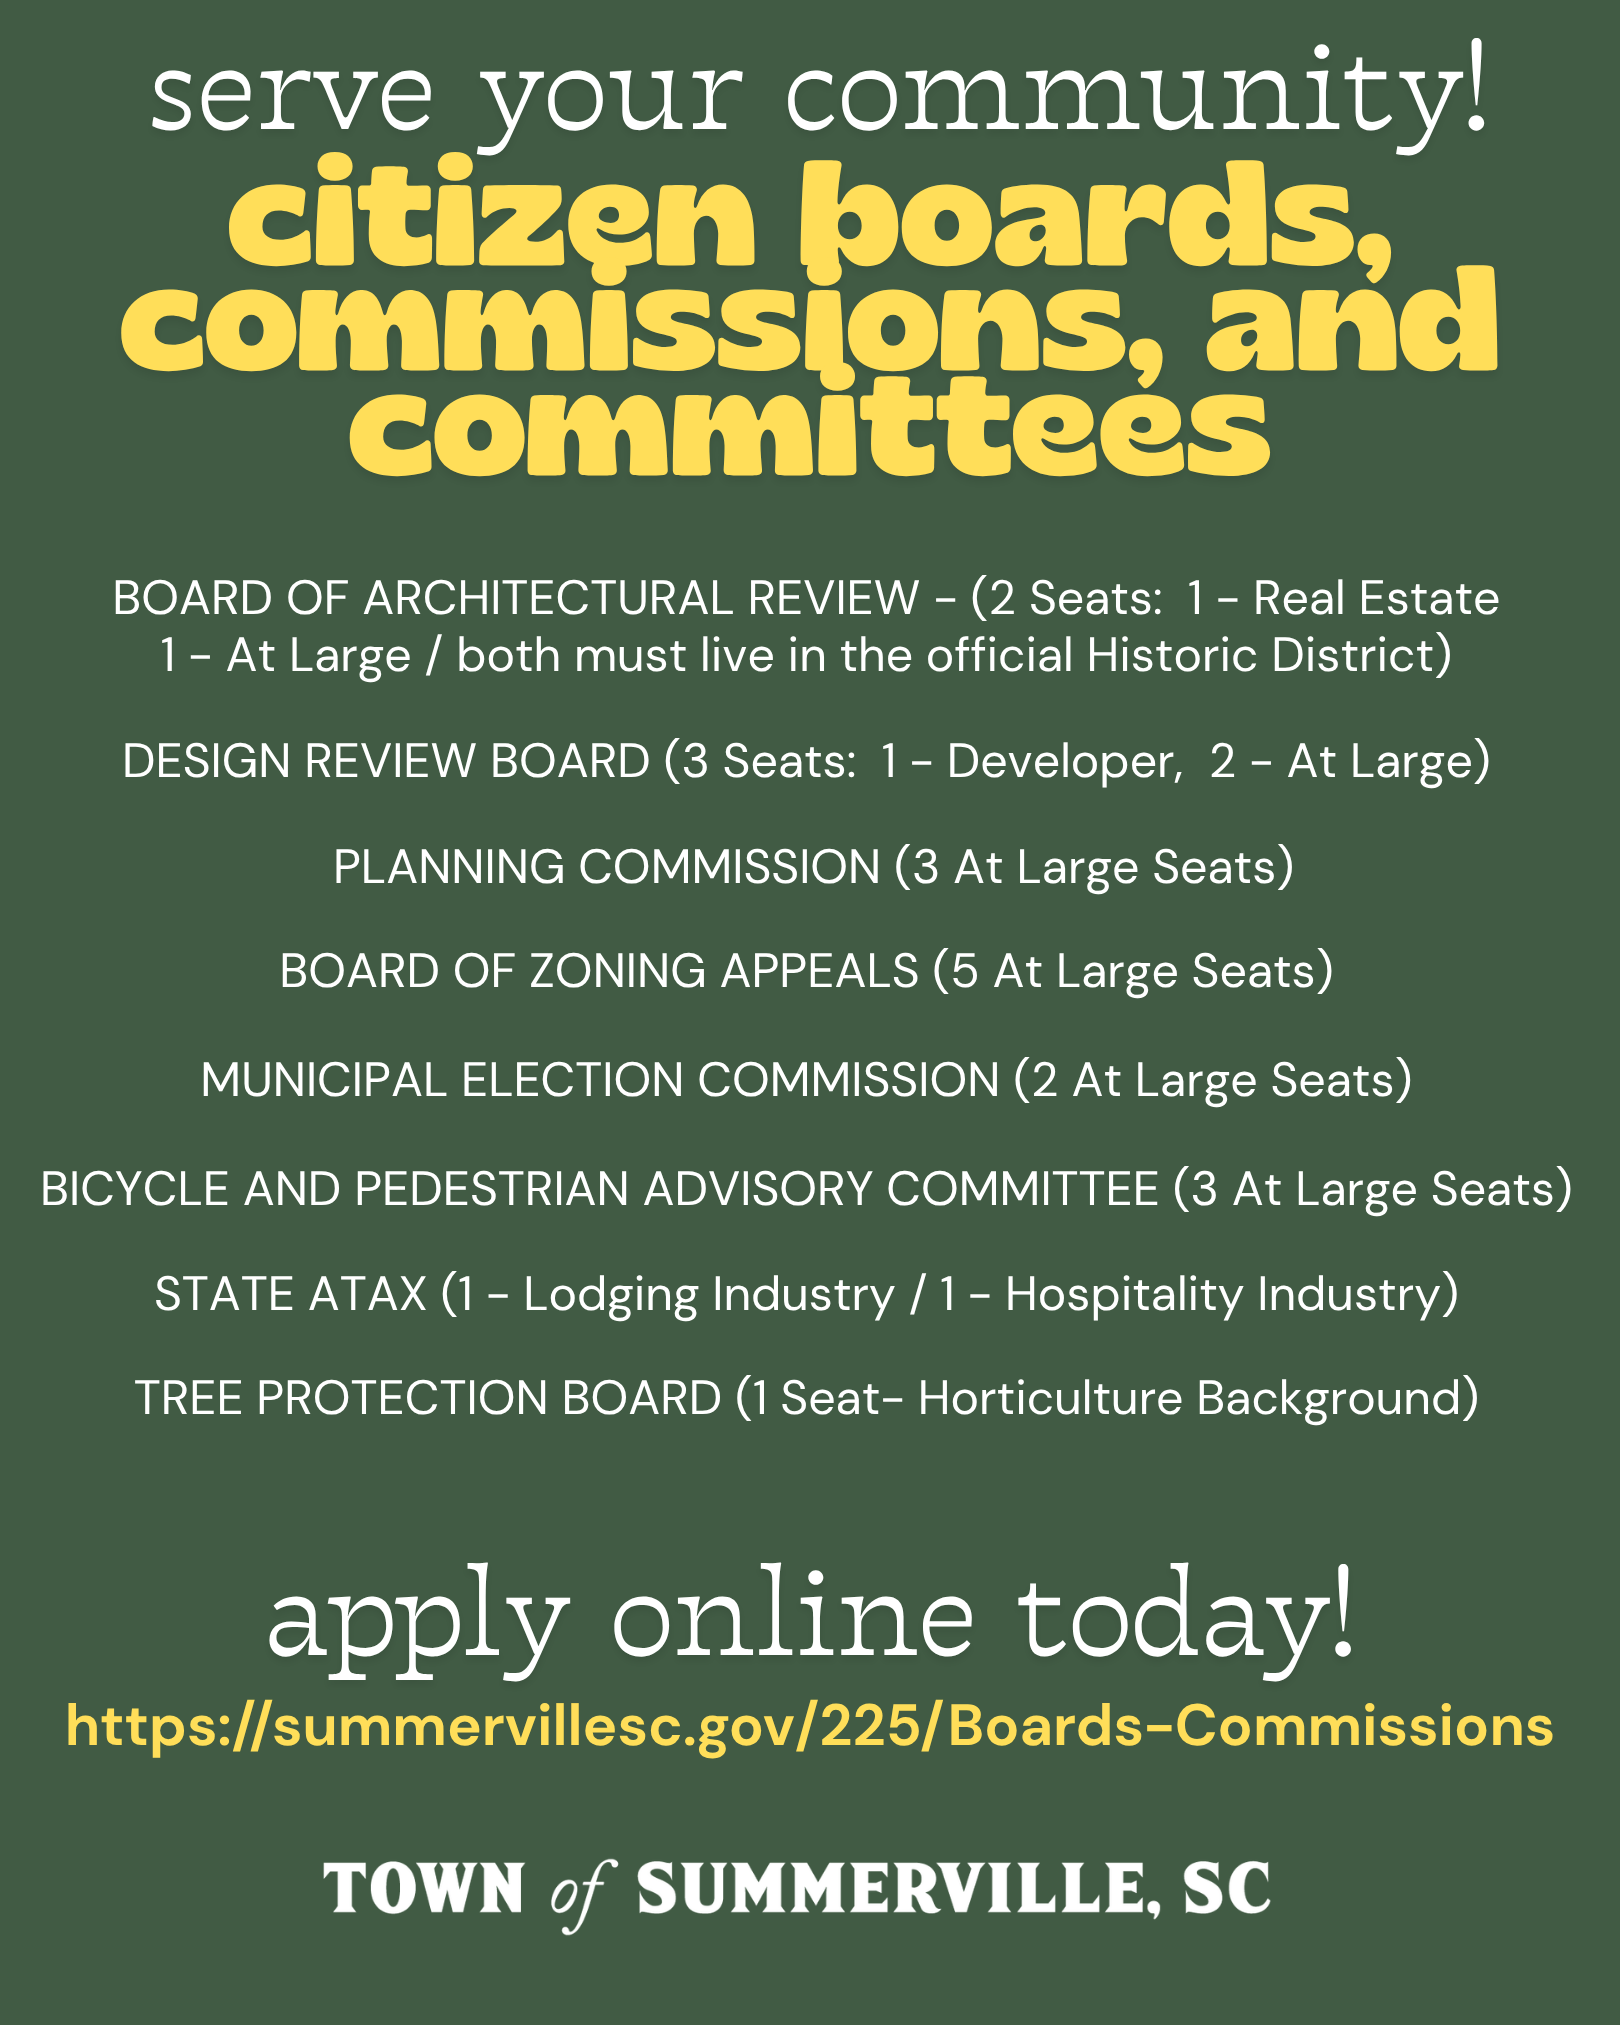
Serve Your Community! Citizen Boards, Commissions, and Committees
September 30, 2026
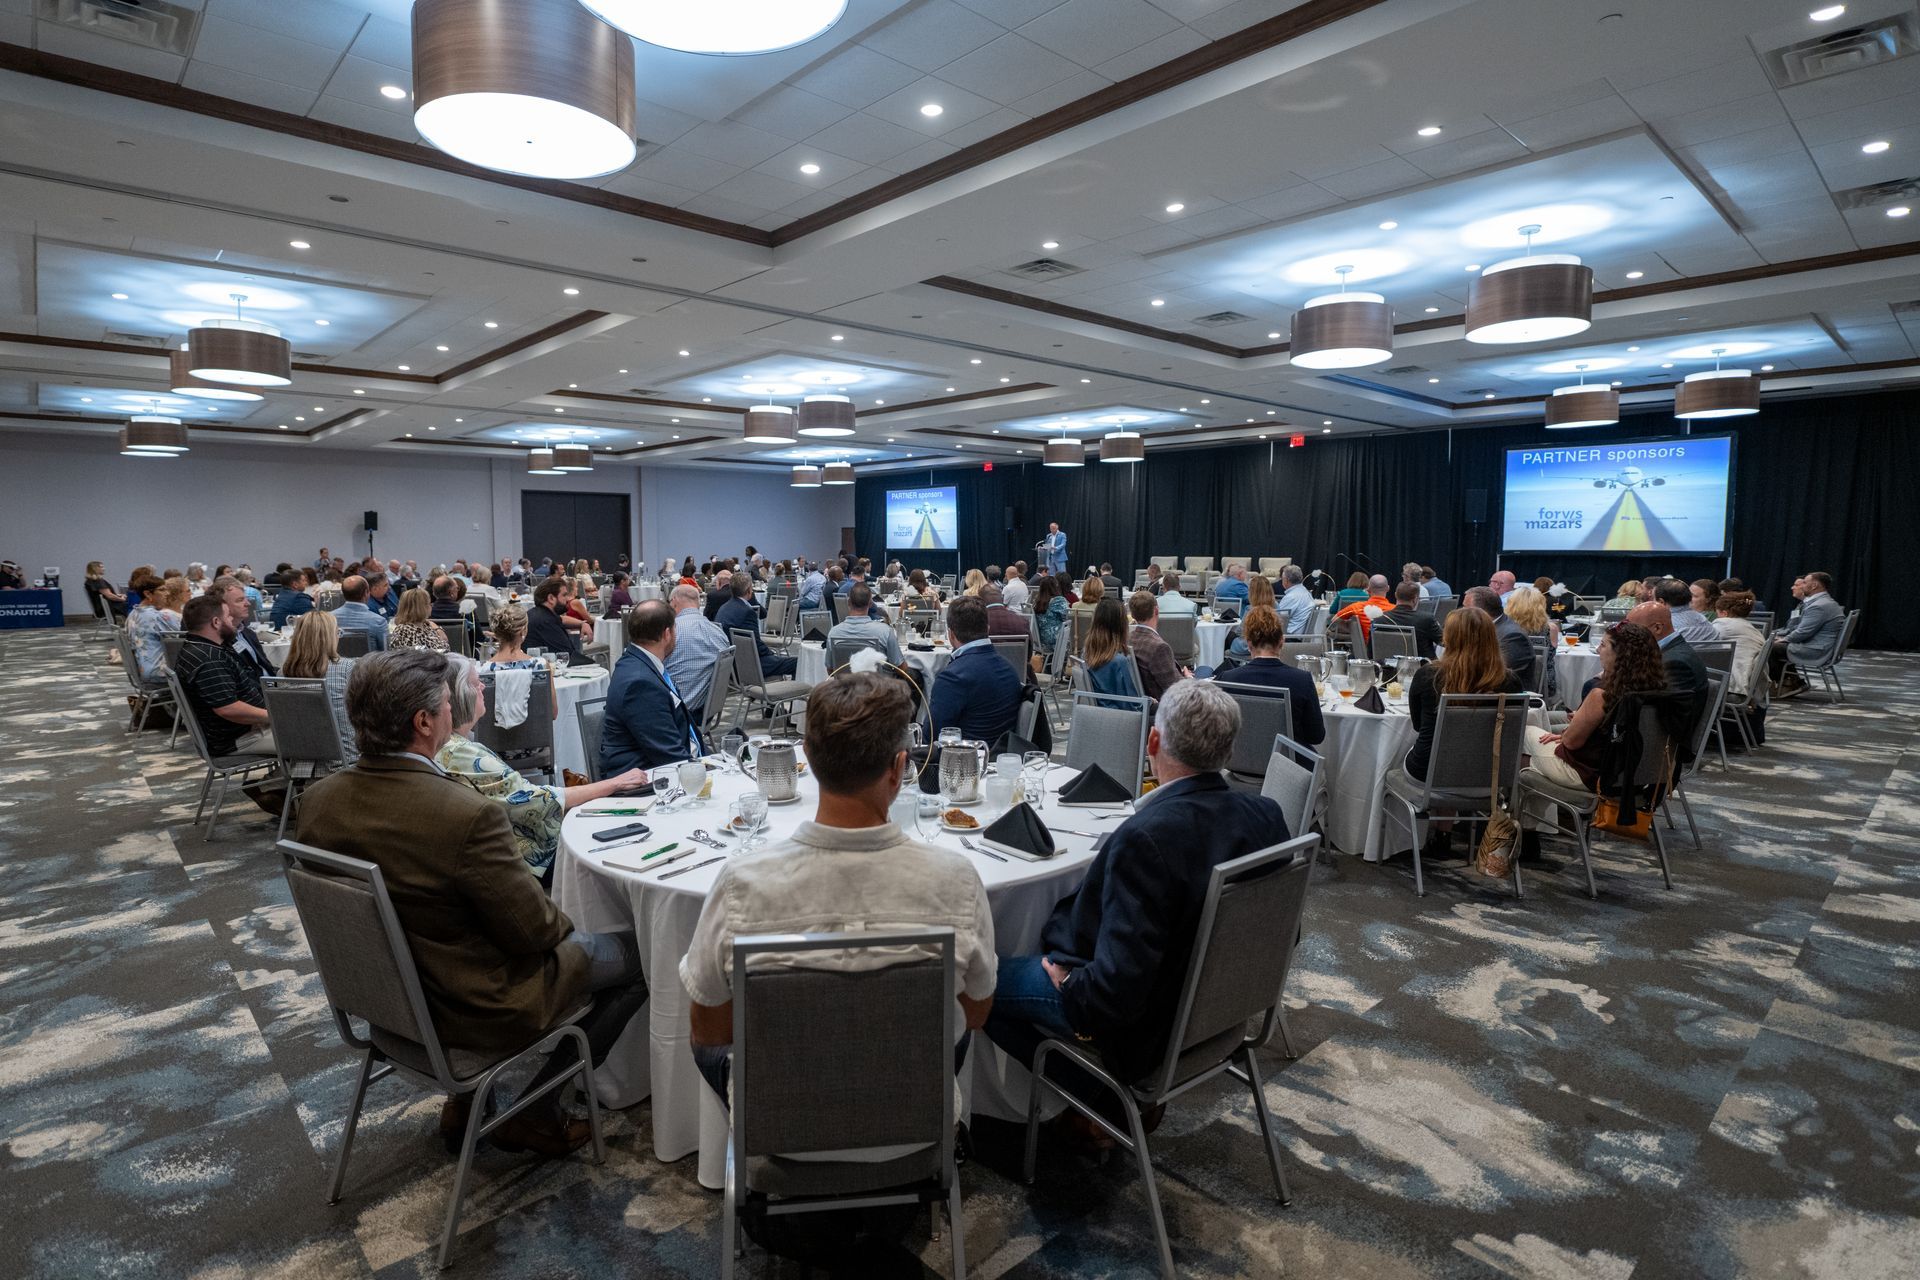
Industry and Workforce Appreciation Luncheon Highlights Aviation’s Role in the Lowcountry